Author

admin

Browsing

I get this question a lot, usually from parents who grew up in a different era or from young adults who assume a “family exception” covers them. The short answer might surprise you. The Legal Drinking Age in Florida is 21, and there is no blanket rule that lets your mom or dad hand you a beer just because you’re at home or out for dinner. Let me walk you through how this actually works, why so many people get confused, and where the real risks show up.

The General Rule in Florida

Florida keeps things pretty firm. To buy, possess, or drink alcohol legally, you need to be 21. That standard ties back to a federal law from the 1980s that pushed every state to set the same age or lose highway funding. So the Drinking law in Florida matches the national number, and there’s no “your parents said yes” loophole written into the main statute.

Here’s the part people miss: some states do allow limited parental exceptions. Florida is not one of the generous ones. A parent’s permission does not automatically make it legal for a minor to drink in a restaurant, at a party, or in a public place.

Why People Get Confused

Confusion usually comes from a few directions:

  • Other states have exceptions. Places like Texas or Wisconsin allow supervised drinking in certain settings. Travelers assume Florida works the same way. It doesn’t.
  • Private home myths. Many folks believe anything goes inside your own house. Private property changes some things, but it doesn’t erase every rule.
  • Old memories. Older relatives remember a time when the drinking age was 18 in parts of the country.
  • Religious or medical uses. People hear about narrow exceptions and assume they apply broadly.

I understand the mix-up. Alcohol laws vary a lot from state to state, and it’s easy to blend them together in your head.

Possible Exceptions Worth Knowing

While Florida is strict, a few narrow situations can come up. These are limited, and they don’t hand parents a free pass:

  • Religious ceremonies may involve small amounts of alcohol in specific contexts.
  • Certain employment settings, like a restaurant, may allow someone under 21 to handle or serve alcohol under supervision, though drinking it is a different story.
  • Tasting for culinary or educational programs can exist under regulated conditions.

None of these equal “a parent allows it, so it’s fine.” That’s the key takeaway.

Quick Comparison Table

Here’s a simple snapshot to keep things clear:

Situation Legal for Under-21 in Florida?
Parent allows drinking at home Generally no
Drinking in a restaurant with parents No
Buying alcohol with a parent present No
Possessing alcohol in public No
Narrow religious/employment/educational contexts Sometimes, with strict limits

When in doubt, assume the answer is no unless a specific, verified exception clearly applies.

The Practical Risks

Let’s talk about what can actually happen, because this matters more than theory.

A minor caught with alcohol can face a misdemeanor charge, fines, community service, and even a driver’s license suspension. That last one stings for a young person just gaining independence.

Parents aren’t off the hook either. An adult who provides alcohol to a minor can face criminal charges. If something goes wrong, like a car crash or injury, the legal and financial fallout can grow fast.

So the “harmless family moment” can turn into a record, a fine, and a lot of stress. I’d rather you know that upfront.

When You Should Seek Legal Advice

General articles like this one help you understand the landscape, but they don’t replace real guidance. Talk to a qualified attorney if:

  • You or your child is facing an underage possession charge.
  • You’re unsure whether a specific exception applies to your situation.
  • You host events where alcohol and young people might mix.
  • You’ve recently moved to Florida and want to confirm the rules where you live.

Laws also change over time, and local enforcement can vary. Always verify current details with an official Florida source or a local professional before you act.

A Quick Note on Everyday Confusion

People often research topics like this the same way they handle other adult responsibilities, whether that’s checking a lease, confirming a background detail, or sorting out a PNP bill payment. It’s all part of staying organized and informed. The habit of double-checking before you commit to something is exactly the mindset that keeps you out of trouble with alcohol laws too.

FAQs

Can my parents legally give me alcohol at home in Florida?

Generally, no. Florida does not offer a broad parental exception, so this can create legal problems for both you and your parent.

Is the Legal Drinking Age in Florida really 21 with no exceptions?

The core age is 21. A few narrow contexts exist, but they’re limited and don’t include casual parental permission.

What happens if a minor gets caught drinking?

Possible outcomes include fines, community service, a misdemeanor charge, and a driver’s license suspension.

Can I trust older advice about the drinking age?

Not always. Rules have changed over the decades, and other states differ. Verify current Florida law before relying on old information.

Do these rules ever change?

Yes. Laws update, and enforcement can shift. Check an official source or ask a local attorney to confirm the latest details.

Staying informed protects you and the people you care about. When it comes to alcohol and anyone under 21 in Florida, the safest move is simple: know the rule, respect it, and verify anything you’re unsure about.
The first two weeks after a Florida car accident can affect more than your physical recovery. What you document, when you seek medical care, and how you communicate with insurance companies may also affect your claim.

At our firm, we help accident victims understand what comes next so they can focus on recovering rather than trying to figure out the claims process alone. Florida also has a specific 14-day rule connected to Personal Injury Protection, or PIP, benefits, making prompt action especially important.

Key Takeaways

  • Seek appropriate medical care promptly after a Florida car accident.
  • Florida’s PIP statute generally requires initial medical services and care within 14 days of the crash for medical benefits.
  • Photograph vehicle damage, injuries, road conditions, and anything else relevant to the collision.
  • Keep medical records, receipts, repair estimates, and insurance correspondence organized.
  • Be careful about statements made to insurance companies or posted publicly.
  • Speaking with a car accident attorney early can help you understand deadlines and preserve important evidence.

Why Do the First 14 Days Matter After a Florida Car Accident?

Florida’s current PIP law provides medical benefits for qualifying treatment when initial services and care are received within 14 days after a motor vehicle accident. Depending on the circumstances and medical determination, the statute provides different benefit limits.

This does not mean every injury becomes obvious immediately.

Neck pain, back pain, headaches, and other symptoms can become more noticeable after the initial shock of a collision has passed. We recommend taking symptoms seriously and obtaining appropriate medical advice rather than assuming discomfort will disappear on its own.

Medical records can also document when symptoms began, what treatment was recommended, and how an injury affects your daily activities.

Document the Accident and Your Losses

Evidence can disappear quickly after a crash.

Vehicles are repaired. Road debris is removed. Surveillance footage may be overwritten. Witnesses may forget important details.

If you can safely do so, preserve photographs and videos from the accident scene. Keep the other driver’s information, insurance details, witness contact information, crash-report information, repair estimates, towing bills, rental-car expenses, and related records.

We also recommend keeping a simple file for medical bills and correspondence from insurers.

Documentation does not automatically determine the outcome of a claim, but it can make it easier to establish what happened and identify the losses associated with the collision.

Be Careful When Speaking With Insurance Companies

An insurance adjuster may contact you soon after an accident and ask questions about the crash or your injuries.

You should be truthful, but you also do not need to guess about facts you do not know. Statements made early in a case can later become relevant if fault or the extent of an injury is disputed.

Our firm regularly deals with insurance companies on behalf of accident victims so our clients can concentrate on their recovery. LawKevin.com notes that Attorney Kevin L. Sullivan II has represented more than 1,000 accident victims throughout Florida.

Do Not Forget Florida’s Lawsuit Deadline

The 14-day PIP requirement is not the same as Florida’s statute of limitations.

Under the 2026 Florida Statutes, an action founded on negligence generally must be commenced within two years. Particular cases can involve different rules or deadlines, so waiting until the deadline approaches can create unnecessary risk.

Contacting a car accident attorney early also allows more time to locate witnesses, preserve evidence, review insurance coverage, and investigate liability.

Conclusion

The days immediately following a Florida crash can be confusing, but a few practical steps can protect both your health and your ability to pursue a claim.

We recommend getting appropriate medical care, documenting the collision, preserving bills and records, and being cautious with insurance communications. Florida’s PIP rules and legal deadlines make timing particularly important.

At our firm, we provide free, no-obligation consultations to accident victims and handle cases on a contingency-fee basis as described on our website. If you have questions after a crash, we can review the circumstances and explain the options that may apply to your case.

Frequently Asked Questions

How long do I have to get medical treatment after a Florida car accident?

For Florida PIP medical benefits, current law generally requires initial services and care within 14 days after the motor vehicle accident.

How long do I have to sue after a Florida car accident?

Florida’s current statute generally establishes a two-year limitations period for negligence actions. Different circumstances can affect deadlines, so case-specific legal advice matters.

Should I photograph my car after an accident?

Yes. Photographs of vehicle damage, the accident scene, road conditions, and visible injuries can help preserve evidence.

When should I contact a car accident attorney?

There is no need to wait for a claim to become complicated. Early legal review can help identify applicable insurance coverage, evidence, and deadlines.

This post was written by a professional at LeavenLaw. Attorney Kevin L. Sullivan II is your auto accident attorney Largo and an experienced personal attorney near you for LeavenLaw. Kevin is proud to serve Florida accident victims that have been injured in auto accidents, motorcycle accident, slip and falls or have suffered any other type of injury caused by negligence. Kevin offers a FREE no-obligation consultation to discuss your claim. There are NO upfront fees or costs and if he does not collect for you, you do not owe him anything.

Passengers are often caught in a difficult position after a car accident. You may have had no control over either driver’s actions, yet you can still be left with medical bills, missed work, pain, and questions about which insurance company should pay.

At The Black Law Company, we help injured people throughout Florida understand their options after auto accidents. For passengers, that often means identifying every applicable insurance policy and determining which driver-or combination of drivers-may be responsible.

Key Takeaways

  • Passengers injured in Florida car accidents may have multiple potential sources of insurance coverage.
  • Florida Personal Injury Protection can apply to passengers, although which policy provides benefits depends on the circumstances.
  • More than one driver may share responsibility for a collision.
  • Medical records, crash reports, photographs, and witness information can help establish an injury claim.
  • Insurance coverage should be investigated before assuming there is only one source of compensation.
  • A Florida car accident attorney can help coordinate claims involving several drivers and insurers.

Can a Passenger Make a Claim After a Florida Car Accident?

Yes. Being a passenger does not prevent you from pursuing available benefits or making a claim when another person’s negligence causes your injuries.

Florida’s Personal Injury Protection statute includes passengers among the people who can receive required PIP benefits from an applicable motor vehicle insurance policy. The law generally provides up to $10,000 in medical and disability benefits, subject to statutory limits, eligibility requirements, and coverage rules. Initial qualifying medical services generally must be received within 14 days after the accident.

The question is often not whether coverage exists, but which policy applies first.

Which Insurance Pays for an Injured Passenger?

Passenger claims can involve several insurance policies.

Depending on the circumstances, we may need to review the passenger’s own auto insurance, insurance belonging to a resident relative, coverage on the vehicle the passenger occupied, and liability coverage available from the driver who caused the collision.

That becomes especially important when two vehicles share responsibility.

For example, imagine one driver runs a red light while another is speeding through the intersection. A passenger injured in the resulting collision did not cause either driver’s conduct, but both drivers’ actions may need to be investigated.

At The Black Law Company, we do not limit the investigation to the first insurance policy presented to us. We examine the accident and available coverage to identify the parties that may be legally responsible.

What Evidence Can Strengthen a Passenger Injury Claim?

A passenger may have an advantage in one respect: there is often less dispute about whether the passenger’s driving caused the accident because the passenger was not operating either vehicle.

However, evidence still matters.

We may review crash reports, photographs, videos, witness statements, medical records, vehicle damage, and insurance documents. Medical documentation is particularly important because it can connect reported injuries and treatment to the collision.

We encourage injured passengers to preserve bills, receipts, discharge instructions, wage information, and communications from insurers.

What If the Driver Who Caused the Crash Has No Insurance?

An uninsured driver does not necessarily end the investigation.

Florida law requires insurers providing qualifying bodily injury liability coverage to offer uninsured motorist coverage, although the named insured can reject that coverage in writing. UM coverage is designed to protect insured people who are legally entitled to recover damages from uninsured motorists.

Whether a passenger has access to UM or underinsured motorist coverage depends on the applicable policies and facts.

The Black Law Company handles both auto accident and uninsured/underinsured motorist claims from its Tampa practice.

Why Can a Car Accident Attorney Help?

Passenger claims can become complicated when several insurers are involved.

We can investigate liability, review policies, collect records, communicate with insurance companies, and evaluate the damages connected to the accident. If an insurer disputes responsibility or undervalues the claim, we can address those issues on the client’s behalf.

Our goal is to give injured passengers a clearer picture of their legal options rather than leaving them to negotiate several insurance claims alone.

Conclusion

Being a passenger does not mean you have to absorb the financial consequences of someone else’s driving decisions.

A Florida passenger injury claim may involve PIP benefits, liability insurance, UM/UIM coverage, or multiple responsible drivers. The right approach depends on how the crash happened and which policies apply.

At The Black Law Company, we represent people injured in Florida auto accidents and help them work through the insurance and liability questions that follow. If you were hurt while riding as a passenger, we can review the circumstances and explain the potential next steps.

Frequently Asked Questions

Can a passenger sue after a Florida car accident?

Potentially. The ability to pursue damages depends on the injuries, available insurance, liability, and other facts surrounding the accident.

Does PIP cover passengers in Florida?

Florida’s PIP statute includes passengers among people who may receive benefits under an applicable policy, subject to statutory coverage and priority rules.

Can both drivers be responsible for a passenger’s injuries?

Yes. Some accidents involve negligence by more than one driver. Liability should be evaluated based on the evidence.

What if I was a passenger in the at-fault driver’s car?

You may still have options. Being in the vehicle of the driver who caused the crash does not automatically make you responsible for that driver’s conduct.

Should I speak with a car accident attorney as a passenger?

Legal guidance can be especially useful when several policies, drivers, or insurance companies are involved.

This post was written by Okoye Morgan Jr., a black attorney and lawyer with extensive knowledge of Tampa car accidents. Okoye is one of the founding partners of The Black Law Company, specializing in personal injury law, trust and estate law, civil litigation law, and criminal defense.

The information provided on this website does not, and is not intended to, constitute legal advice. All information, content, and materials available on this site are for general informational purposes only. Information on this website may not constitute the most up-to-date legal or other information. This website contains links to other third-party websites. Such links are only for the convenience of the reader, user or browser; the ABA and its members do not recommend or endorse the contents of the third-party sites.

People tend to assume that dying without a will means their family sorts things out informally. In reality it means a statute sorts things out, applying a fixed formula that has no knowledge of the family it is being applied to.

Utah’s intestate succession rules live in the state probate code. They are not arbitrary, and in the most common situation they produce a sensible result. But they were written to cover every family in the state with one set of rules, and the further a family sits from the standard shape, the further the outcome drifts from what anyone would have wanted.

The case where the default works fine

A married couple, children all from that marriage, no prior spouses. One dies without a will. Under Utah law the surviving spouse takes the entire intestate estate. Nothing goes to the children yet, which is almost always what the couple would have chosen anyway.

This describes a large share of Utah households, and it is why the absence of a will sometimes causes no visible problem at all. The formula happened to match the intent.

Where it stops working

Change one fact. The deceased spouse has a child from an earlier relationship.

Now the surviving spouse no longer takes everything. Utah’s statute gives the spouse a set dollar amount off the top plus a share of the remaining balance, with the rest passing to the deceased person’s descendants.

The practical consequence is what matters. A surviving spouse can end up co-owning the family home with a stepchild she has a difficult relationship with, or with a stepchild she has never met. Neither of them chose this. The statute chose it. And undoing it requires the cooperation of the person who benefits from leaving it alone.

Given how common remarriage is, and how many Utah households include children from more than one relationship, this is not an edge case.

Unmarried partners receive nothing

Utah’s intestate rules distribute to spouses, descendants, parents, and then outward to siblings and more distant relatives. A long-term partner who is not legally married appears nowhere in that list. Neither does a stepchild who was never legally adopted, no matter how long they were raised in the home.

Both of those omissions surprise families constantly, and neither can be corrected after the fact.

Someone still has to be appointed

Without a will there is no nominated personal representative, so the court appoints one according to a statutory priority order. Adult children share equal standing, which means that when several of them want the role, or when none of them do, the appointment itself becomes the first dispute rather than an administrative formality.

A will naming a personal representative and an alternate removes that question entirely, and it is the shortest paragraph in the document.

Minor children are the real reason to act

For parents of young children, guardianship outweighs everything financial. A will is where a parent nominates who raises their children if both parents are gone. Absent that nomination, a judge decides among whoever petitions, working from a best-interests standard and whatever evidence gets presented.

Judges in Utah’s district courts handle these carefully. But a judge choosing between two sets of relatives, in a hearing, with limited information, is a poor substitute for parents who simply wrote the name down.

The financial side matters too. Without direction, a minor’s inheritance is typically held in a conservatorship and handed over outright at eighteen. Very few parents, asked directly, would choose to give an eighteen-year-old a lump sum with no strings attached. A modest trust provision solves it.

The threshold is lower than people think

Getting a will in place is not a complex or expensive undertaking for most Utah families. What it requires is one honest conversation about who should raise the children, who should be in charge, and how property should be divided when it cannot simply be split down the middle.

For anyone wanting to see how the state’s rules would apply to their own situation before booking a consultation, trustlawutah.com is one of the Utah firm sites that lays out the succession framework in plain language rather than statute citations.

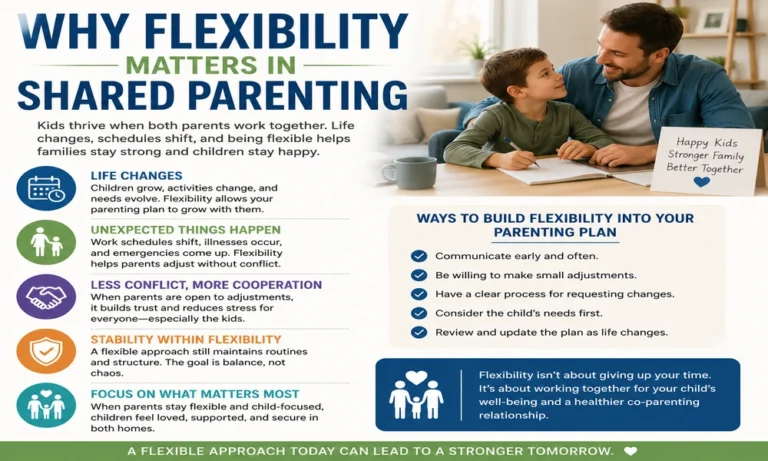
Shared parenting can provide children with meaningful relationships with both parents, but making a shared schedule work in everyday life often requires flexibility. Work commitments, school activities, holidays, health needs, and unexpected events can all affect a family’s routine. A parenting arrangement that allows reasonable adjustments can make these changes easier to manage.

Children’s Needs Can Change

A parenting schedule that works well when a child is young may not be suitable several years later. School schedules, extracurricular activities, friendships, and changing developmental needs can affect how parenting time should be organized.

Parents who remain open to reasonable changes can adjust their arrangements as their children grow while maintaining consistency where it matters most.

Work and Family Schedules Can Shift

Parents may have changing work hours, business trips, appointments, or other obligations. Rigid schedules can create unnecessary conflict when unexpected changes occur.

Flexibility allows parents to communicate about occasional adjustments without treating every scheduling issue as a major dispute. However, flexibility does not mean that established parenting orders or agreements should simply be ignored. Changes should be handled through communication and, when necessary, appropriate legal procedures.

Flexibility Can Reduce Conflict

Parents may disagree about many aspects of co-parenting, but minor scheduling issues do not always need to become prolonged disputes. A willingness to make reasonable accommodations can help parents focus on their children rather than repeatedly arguing about logistics.

Clear communication is especially important. Parents should discuss changes in advance when possible and keep conversations focused on practical arrangements and the child’s needs.

Safety and Stability Still Matter

Being flexible does not mean accepting arrangements that are unsafe or disruptive. A child’s health, safety, welfare, and overall stability should remain central to parenting decisions.

Parents should also consider school attendance, medical appointments, established routines, and other commitments when making changes to a schedule.

Build Flexibility Into the Parenting Plan

Parents can make shared parenting easier by addressing potential changes when creating their parenting plan. They may establish procedures for requesting schedule swaps, handling holidays, managing transportation, and dealing with unexpected circumstances.

A successful shared parenting arrangement needs both consistency and flexibility. Clear expectations provide stability, while reasonable adjustments allow families to respond to real-life changes. When parents communicate respectfully and keep the child’s best interests at the center of their decisions, flexibility can make shared parenting more practical and sustainable.

This post was written by a professional at the Law & Mediation Offices of Dan DeSario & Associates, a full-service law firm in Southern California specializing in family law, high-conflict divorce, child custody & visitation, domestic violence / restraining order defense, guardianships, private mediation, trials/litigation, and minor’s counsel appointments. As one of the leading law firms near you, we serve clients throughout Southern California, including Los Angeles County, Beverly Hills, West Los Angeles, San Fernando Valley (Van Nuys, Chatsworth), Ventura County, Long Beach, Redondo Beach, Manhattan Beach, Marina del Rey, Santa Barbara (existing cases), and San Diego (existing cases). If you are looking for a family law attorney in Marina del Rey, our experienced team provides expert guidance and reliable solutions, making us a trusted choice for family law and mediation services focused on quality, value, and performance.

Unexpected medical expenses can place significant financial strain on individuals and families, even when they have health insurance. A sudden illness, injury, or emergency procedure may result in costs that were not anticipated, making it difficult to keep up with everyday expenses.

Understanding how medical bills contribute to financial hardship highlights the importance of planning for healthcare costs whenever possible.

High Out-of-Pocket Expenses

Health insurance can help reduce medical costs, but many policies still require patients to pay deductibles, copayments, coinsurance, or expenses for services that are not fully covered. These out-of-pocket costs can add up quickly, especially when hospitalization, surgery, or specialized treatment is involved.

Loss of Income During Recovery

Medical emergencies often affect a person’s ability to work. Time away from work for treatment, recovery, or rehabilitation may result in reduced income or unpaid leave. For households that rely on a single income or have limited savings, even a temporary interruption in earnings can make it difficult to pay rent, utilities, loan payments, and other essential expenses.

Ongoing Healthcare Costs

The financial impact of a medical condition frequently extends beyond the initial hospital visit. Prescription medications, follow-up appointments, physical therapy, medical equipment, and long-term care may continue for weeks, months, or even years. These recurring expenses can place additional pressure on a household budget long after the original medical emergency.

Increased Reliance on Credit

When savings are insufficient, some individuals turn to credit cards, personal loans, or other forms of borrowing to cover medical expenses. While this may provide temporary financial relief, accumulating debt can lead to higher interest costs and make it more difficult to regain financial stability over time.

The Importance of Financial Planning

Building an emergency fund, reviewing health insurance coverage, and maintaining a realistic household budget can help reduce the financial impact of unexpected medical bills. Although not every medical emergency can be anticipated, preparing for unforeseen expenses can improve a family’s ability to manage financial challenges without relying heavily on debt.

Final Thoughts

Unexpected medical bills can affect far more than healthcare costs alone. They may reduce savings, interrupt income, increase debt, and delay important financial goals. By understanding these potential challenges and planning whenever possible, individuals and families can strengthen their financial resilience and better navigate the economic effects of unexpected medical events.

This post was written by Trey Wright, an experienced bankruptcy lawyer Jacksonville FL! Trey is one of the founding partners of Bruner Wright, P.A. Attorneys at Law, specializing in bankruptcy law, estate planning, and business litigation.

The information provided on this website does not, and is not intended to, constitute legal advice; all information, content, and materials available on this site are for general informational purposes only. Information on this website may not constitute the most up-to-date legal or other information. This website contains links to other third-party websites. Such links are only for the convenience of the reader, user or browser; the ABA and its members do not recommend or endorse the contents of the third-party sites.

In a personal injury case, evidence plays a critical role in determining liability and the value of a potential settlement. The stronger and more organized the evidence, the easier it may be to demonstrate how an accident occurred, the extent of the injuries, and the financial impact on the injured person. While every case is unique, certain types of evidence consistently carry significant weight during settlement negotiations.

Medical Records and Treatment Documentation

Medical records are often among the most important pieces of evidence in a personal injury claim. They establish the nature of the injuries, document the treatment received, and provide a timeline linking the injuries to the accident. Records of follow-up appointments, rehabilitation, prescriptions, and medical expenses also help demonstrate the ongoing effects of the injury.

Photos and Videos from the Scene

Visual evidence can provide a clear picture of the accident and its aftermath. Photographs or videos of the accident scene, property damage, hazardous conditions, and visible injuries may help explain how the incident occurred. Images taken shortly after the event are often especially valuable because they capture conditions before changes are made.

Witness Statements

People who witnessed the accident can provide independent accounts of what happened. Their observations may help confirm details such as how the accident occurred, weather conditions, or the actions of those involved. Credible witness statements can strengthen a claim by supporting other available evidence.

Police or Incident Reports

If law enforcement or another authority responded to the accident, an official report may include important details such as the date, time, location, involved parties, and initial observations. Although these reports do not necessarily determine fault, they often serve as useful reference documents during the claims process.

Financial Records and Proof of Losses

Settlement discussions frequently consider the financial consequences of an injury. Documents such as medical bills, repair estimates, wage statements, and records of lost income help demonstrate the economic impact of the accident. Keeping organized records can make it easier to calculate damages accurately.

Final Thoughts

No single piece of evidence guarantees a favorable settlement. Instead, the strongest claims are typically supported by a combination of medical documentation, photographs, witness accounts, official reports, and financial records. Gathering and preserving evidence as early as possible can help create a clearer picture of the accident and support informed settlement negotiations.

This article was written by Alla Tenina. Alla is a top San Fernando Valley personal injury lawyer, and the founder of Tenina Law. She has experience in bankruptcies, real estate planning, and complex tax matters. The information provided on this website does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only. Information on this website may not constitute the most up-to-date legal or other information. This website contains links to other third-party websites. Such links are only for the convenience of the reader, user or browser; the ABA and its members do not recommend or endorse the contents of the third-party sites.

After property damage occurs, timing plays a critical role in whether a claim is approved, reduced, or denied. In many cases, waiting even 48 hours to report or document damage can significantly weaken a property claim and create avoidable complications.

Why the First 48 Hours Matter

The first two days after a loss are when evidence is at its strongest. Damage is fresh, conditions are unchanged, and documentation is easier to verify. Insurance processes often rely heavily on early reporting to assess the cause and extent of loss accurately.

Delays can raise questions about what happened and when it occurred.

Loss of Critical Evidence

Physical evidence can change quickly after an incident. Water damage may spread, debris may be moved, and environmental factors can alter the scene. Without immediate documentation, it becomes harder to prove the original extent of the damage.

Photos, videos, and written records taken early can make a significant difference.

Increased Risk of Claim Disputes

Waiting to report damage can lead to disputes with insurers. Late reporting may create uncertainty about whether additional damage occurred after the initial event. This can result in reduced payouts or partial claim denials.

Timely reporting helps establish a clear timeline of events.

Missed Documentation Opportunities

Early reporting allows professionals to inspect the property under original conditions. Once repairs begin or conditions change, important details may be lost.

Delays can limit the ability to fully assess the scope of damage.

Policy Compliance Issues

Many insurance policies require prompt reporting of property damage. Failing to notify the insurer within a reasonable timeframe may affect eligibility for coverage or complicate the claims process.

Understanding policy requirements is essential to avoid unnecessary setbacks.

Final Thoughts

Waiting just 48 hours after property damage can significantly impact the strength and success of a claim. Early documentation, prompt reporting, and clear communication help preserve evidence and reduce the risk of disputes. Acting quickly is often the most important step in protecting your property claim outcome.

This post was written by Kelly-Ann Jenkins of Jenkins Law P.L. Kelly-Ann is an insurance claim Lawyer. The information on this site is not intended to and does not offer legal advice, legal recommendations, or legal representation on any matter. Hiring an attorney is an important decision that should not be based on advertising. You need to consult an attorney for legal advice regarding your situation. Click here to learn more!

The information provided on this website does not, and is not intended to, constitute legal advice; all information, content, and materials available on this site are for general informational purposes only. Information on this website may not constitute the most up-to-date legal or other information. This website contains links to other third-party websites. Such links are only for the convenience of the reader, user, or browser; the ABA and its members do not recommend or endorse the contents of the third-party sites.

Careful preparation helps people present clear facts when seeking a proper claim. Every document carries value while legal guidance keeps each step easy to follow. Accurate records support steady progress through simple planning without unnecessary confusion. Trusted medical negligence solicitors can provide suitable direction from the beginning.

Strong Claim Foundation

A strong claim begins with clear facts collected at the right time. Every document should match the actual event without missing details. Reliable records reduce confusion while medical negligence solicitors provide legal direction during each important stage. Steady preparation also improves confidence before every required step.

Records Supporting Case Strength

Clear records help explain every concern with simple facts. Written notes, dated papers, clear statements, relevant files, and proper timelines create a dependable picture for careful review.

  • Keep original papers safely for future reference during every important stage.
  • Write important details clearly after every related event without delay.
  • Gather supporting records from trusted sources before making any claim.
  • Check every document carefully before sharing important information with advisers.
  • Maintain clear timelines showing steady progress throughout the entire matter.

Timely Action Matters

Prompt action helps protect valuable information before important details become unclear. Early preparation allows careful checking of records with proper attention. Delays may create unnecessary difficulty during review. Strong legal planning supports smooth progress while reducing avoidable problems across every stage.

Honest Statements Matter

Truthful statements strengthen trust throughout the entire process. Every fact should remain clear without changing important details later. Simple language makes each point easier for others to understand. Careful legal review helps present accurate information with confidence while avoiding unnecessary confusion.

Careful Case Preparation

Proper preparation builds confidence before every required stage. Each document should support the main claim through clear facts alone. Patient effort often creates stronger results because every detail receives suitable attention. Balanced legal guidance encourages steady progress while keeping every step focused on reliable information.

Every claim becomes stronger through careful planning supported by truthful records plus timely action. Clear facts create greater confidence while steady preparation reduces avoidable problems before review. Suitable guidance keeps every stage focused on practical goals with simple direction. Careful effort often leads to a stronger outcome built on trust plus accurate information.

FAQs

What records should support a negligence claim properly today?

Clear papers with accurate facts strengthen every claim during careful review.

Why should action begin soon after a serious concern arises?

Early preparation protects valuable details before important information becomes unclear.

Who helps prepare reliable negligence claims with proper guidance available?

Qualified advisers provide clear direction through each important stage successfully.

After an accident, one of the first questions people ask is whether they should hire a personal injury lawyer or handle the claim themselves. It is a fair question, and the honest answer depends on the severity of the injury, the value of the losses, and how clearly the other party is at fault.

The general rule: if your injury required medical treatment beyond a basic ER visit, caused you to miss work, or left you with any lasting effects – hire a personal injury lawyer. Most take cases on contingency, meaning no upfront cost, and studies consistently show that represented claimants recover significantly more than those who go it alone.

When You Should Definitely Hire One

Situation Why a Lawyer Is Essential
Serious or permanent injury Maximum compensation requires expert valuation of future losses
Disputed liability Insurers will fight harder when fault isn’t crystal clear
Multiple parties involved Identifying all liable parties and coordinating claims is complex
Employer or government involved Workers’ comp and government claims have unique rules and deadlines
Insurance company acting in bad faith Lowball offers, delays, and denials require legal pressure
You’ve been approached to sign a release Once signed, your right to sue is gone – get legal review first

When You Might Be Okay Without One

Minor fender-benders with no injury and a clear at-fault driver are often handled directly with the insurer. If your medical bills are under $1,000, liability is undisputed, and you’re fully recovered – the math on a contingency fee may not work in your favor. That said, always at least consult a lawyer before signing anything. Consultations are free.

What a Personal Injury Lawyer Does From Day One

From the moment you hire them, a personal injury attorney takes the burden off your plate:

They send a spoliation letter to preserve evidence – surveillance footage, vehicle black boxes, and accident reports can disappear quickly. They communicate directly with all insurance companies so you don’t accidentally say something that damages your claim. They coordinate with your doctors to ensure injuries are properly documented and linked to the accident. They calculate the full value of your claim – including future medical costs and long-term impact on your earning capacity.

How Contingency Fees Work – In Plain English

You pay nothing to hire a personal injury lawyer. Their fee is a percentage of whatever you recover – typically 33% if the case settles before trial, and 35-40% if it goes to court. If you recover nothing, they get nothing.

This means your lawyer is financially motivated to maximize your settlement. It also means they won’t take cases they don’t believe in – if a firm agrees to represent you, that’s already a signal your case has merit.

What Factors Affect What Your Case Is Worth

Factor How It Affects Value
Severity of injury More serious injuries = higher medical costs and pain/suffering
Permanence of harm Lasting disability or disfigurement significantly increases value
Medical expenses (past + future) Direct economic damages – documented and calculated
Lost wages and earning capacity Includes future income lost due to injury
Clarity of fault Clear liability = stronger settlement position
Quality of documentation Photos, reports, and medical records strengthen every argument
Jurisdiction Some states cap damages; jury tendencies vary by location

The Hiring Process – Step by Step

Step 1: Call for a free consultation – most firms offer same-day or next-day consultations, by phone or in person.

Step 2: The attorney evaluates liability, damages, and likely recovery. They’ll tell you honestly if your case is worth pursuing.

Step 3: Sign a retainer agreement. This formalizes the contingency arrangement and authorizes the attorney to act on your behalf.

Step 4: Your lawyer takes over. You focus on recovering; they handle the legal and insurance side.

Step 5: Settlement negotiations or litigation – most cases settle. If the insurer won’t offer fair value, your lawyer files suit.

Mistakes People Make When Hiring (or Not Hiring)

Waiting too long – every state has a statute of limitations, usually 2 to 3 years. Waiting can also let evidence disappear.

Accepting the first settlement offer – initial offers are almost always low. They’re designed to close the case before you know what it’s worth.

Giving a recorded statement to the other driver’s insurer without counsel – insurers are trained to find inconsistencies that reduce your claim.

Hiring a generalist instead of a personal injury specialist – the nuances of accident reconstruction, medical documentation, and insurer tactics require specific experience.

Quick Checklist Before Your First Call

Seek medical care and get all injuries documented, even if you feel fine – symptoms can appear days later.

Photograph the scene, your vehicle, your injuries, and anything relevant to how the accident happened.

Get the other party’s name, insurance information, and contact details. Collect witness names if possible.

Do not post about the accident on social media – insurers monitor this.

Call a personal injury lawyer before calling your own insurer to report the claim.